


Related solution
Grantee & Portfolio Intelligence
Connect partner evidence with agreed measures and portfolio decisions.
Explore the solution →


Live webinar: Wednesday, October 7, 2026 | 9:00 AM PT
Building context across your data. In 30 minutes, see how to connect data and definitions across teams, with the right permissions and governance, so scattered data points become intelligence your teams and AI can actually use.
Save your spot (free)USE CASE / PRACTICAL GUIDE
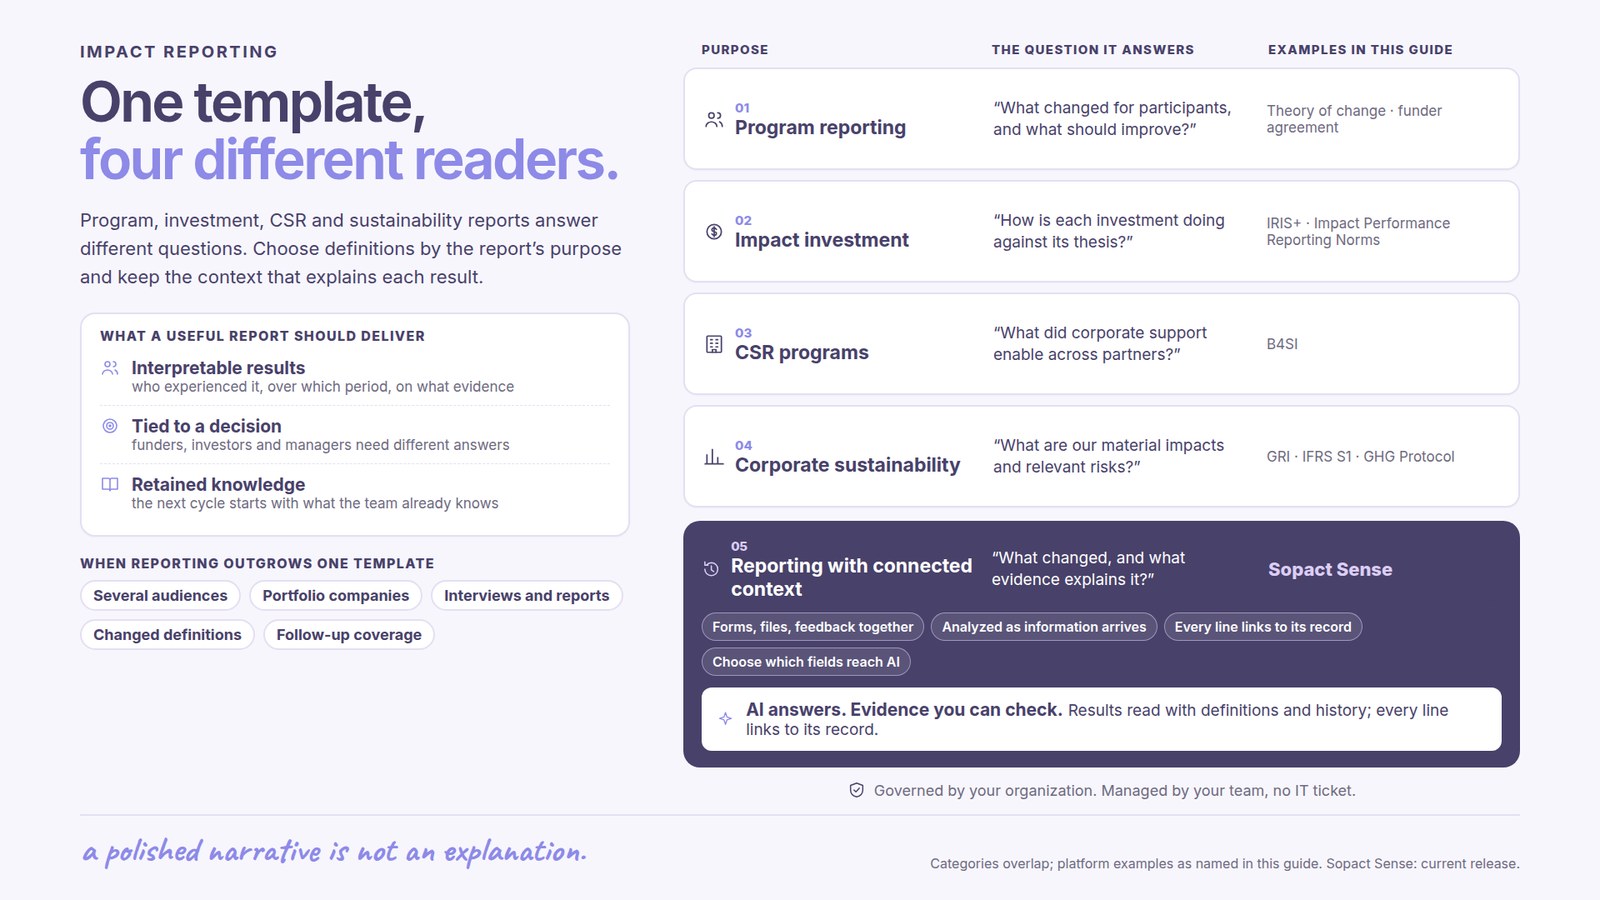
Impact reporting explains the changes an organization contributes to, the evidence behind those changes and what the findings mean for its audience. A useful report connects results with purpose, scope and decisions. Nonprofits, impact investors and corporate teams need different reports because they have different responsibilities and questions to answer.
A nonprofit may need to understand participant outcomes, an investor the performance of portfolio companies, and a CSR team the results of community funding. Sustainability reporting adds the organization’s wider impacts and, for investor-focused disclosures, relevant financial risks and opportunities. Applying one template or one set of metrics to all four can obscure the results.
AI makes it easier to analyze surveys, interviews, spreadsheets and long reports together. The quality of the answer depends on the context: agreed definitions, populations, periods, methods and the purpose of the work. Sopact connects that evidence so reporting can explain what changed and support current decisions, rather than simply generate a polished narrative.
Know who will use the report and which decision it supports.
Keep populations, periods and calculation rules explicit.
Explain the result with sources, commitments and history.
An impact report should explain the purpose of the work, who or what it covers, the activities delivered, the outcomes observed and the evidence behind those outcomes. Include the reporting period, relevant resources, limitations and the decisions the findings support. Distinguish what happened from what the organization can credibly claim to have caused.
For example, “30 of 48 training completers who answered a three-month follow-up reported employment” is more useful than “63% employment impact.” It identifies the population, timing and response base, and it leaves room to explain missing follow-up and other influences.
Use the impact report template and worked sample for a report structure, or browse impact report examples to explore presentation. For a specific audience, see nonprofit impact reports, donor reporting or grant reporting. The sections below explain how context and shared definitions make those reports trustworthy.
The core value of reporting is a credible understanding of performance that someone can use. Faster document production helps, but it does not resolve ambiguous measures, missing context or a report that answers the wrong question.
A useful report makes clear who experienced the result, over which period and with what evidence. Shared definitions and source traceability let readers understand a claim and the team explain it.
A funder needs to understand progress and support needs; an investor needs performance against the impact thesis; a program manager needs the implications for delivery. Tailor the account to that purpose while keeping the underlying facts consistent.
Reporting should reuse evidence already collected during the work. Retain the definitions, reasoning and prior decisions so the next cycle starts with what the organization knows. AI is useful when it helps examine that evidence and explain the result, not simply when it writes more quickly.
| Reporting purpose | Question to answer | Context to retain |
|---|---|---|
| Nonprofit program | What changed for participants, and what support should improve? | Program purpose, cohort, baseline, service received, follow-up coverage and participant voice. |
| Impact investment | How is each investment performing against the impact thesis? | Company activity, target stakeholders, outcome definitions, investment timing, contribution and risk. |
| CSR programs | What did corporate support enable across community partners? | Commitments, disbursements, valuation rules, partner scope, participation and program-specific outcomes. |
| Corporate sustainability | What are the organization’s material impacts and relevant sustainability risks? | Entity and site boundaries, material topics, reporting basis, methods, data coverage and accountable owners. |
These purposes can overlap within one organization. A corporate foundation may publish a nonprofit-style program report that contributes to a parent company’s CSR account. An impact fund may also have sustainability disclosures. Keep each report’s boundary and audience explicit instead of assuming one set of figures answers every question.
For nonprofit programs, begin with the theory of change, funder agreement and measures that fit the service. There is no need to apply an investment metric catalog to every participant outcome.
For impact investments, IRIS+ Core Metrics Sets help select indicators around investment objectives. The Impact Performance Reporting Norms address how investors communicate impact performance. These are different jobs: choosing a metric and explaining performance.
For corporate community investment, B4SI helps organize contributions and results. Corporate sustainability reporting may draw on GRI for organizational impacts, while IFRS S1 addresses sustainability-related risks and opportunities relevant to providers of capital. The GHG Protocol provides accounting guidance for emissions inventories. Select the reference and version for the actual reporting requirement; these approaches are not interchangeable.
A reporting data dictionary is an agreement about what each measure means and how it may be used. It should let two colleagues interpret the same result consistently. A column label such as “beneficiaries” or “jobs” is not enough.
Write the question the measure must answer and identify what one record represents: a participant, service visit, company, grant payment or site-month. Mixing these units is a common reason totals become misleading. A person can attend many sessions; a company can receive several investments.
Give the measure a plain-language definition, unit, reporting period, included population and exclusions. For a rate, specify the numerator and denominator. For repeated measures, state the starting point and follow-up window. Record whether evidence is observed, self-reported, estimated or independently verified.
Specify which values may be summed, which require deduplication and which should remain separate. Calculate combined rates from compatible underlying counts rather than averaging percentages. Keep commitments separate from payments, unique people separate from visits, and portfolio-company results separate from claims about an investor’s contribution.
Retain the survey question, source document or transaction reference, calculation method and review responsibility. If a standard or funder definition applies, record its name and version. An external metric code is a reference to a definition, not a substitute for understanding it.
Record when a definition or method changes and whether earlier figures can be restated. Do not silently compare a new measure with an old one. Keep the original evidence and the explanation so a later reviewer can understand the difference.
The examples below are illustrative reporting designs, not customer results or prescribed standard definitions.
Define: the proportion of usable respondents who report paid employment in the agreed six-month follow-up window. Record the eligible cohort, employment definition, response date, numerator, denominator and source question. Show follow-up coverage separately.
Interpret: if 48 of 80 respondents report employment from 100 people due, the result is 60% among respondents with 80% coverage. It is not a complete employment rate for all 100 people. Participant comments can explain barriers; intake and mentoring history can show which support those respondents received.
Use: a program lead can investigate unmet support needs, while a funder receives the outcome with its coverage and limitations. The same evidence serves both audiences without changing the definition.
Define: whether the measure describes year-end headcount, average full-time-equivalent employment or net change over a period. Record employee and contractor treatment, company, geography, dates, source and any acquisitions that change the reporting boundary.
Interpret: growth after an investment does not by itself show how many jobs the investor caused. Preserve the investment date, business model, impact thesis and evidence of financial or non-financial contribution. Separate company performance from the investor’s role.
Use: the fund can discuss progress against the company’s agreed objective and compare appropriately similar businesses. A single “jobs supported” total without these distinctions hides more than it explains.
Define: cash disbursed as payments made in the reporting period, with currency, funding entity, recipient and transaction source. Keep commitments and partner expenditure as separate measures. For reach, distinguish unique people receiving a defined service from repeat attendances.
Interpret: a payment to a corporate foundation and its onward grant should not both inflate the same corporate contribution total. Two partners’ participant counts should not be described as unique portfolio reach unless overlap has been addressed.
Use: leadership can see resources delivered, partner progress and evidence gaps. Program-specific outcomes remain alongside common portfolio measures.
Define: electricity consumption in kWh by site and period, including the organizational boundary, source bills or meter readings and treatment of missing data. Keep activity data separate from calculated emissions. For emissions, retain the applicable factor, source, year, unit and accounting method.
Interpret: lower electricity use may reflect efficiency, reduced production or a change in included sites. Context determines whether a year-on-year comparison is meaningful. Location-based and market-based Scope 2 results need their respective methods; they should not be mixed into one unexplained trend.
Use: operations can investigate the change, and the sustainability team can report it on the chosen basis. Specialist calculation and disclosure requirements remain part of that process.
The four examples are shown below as finished reports, each with its sources, its data dictionary and what each report panel adds.
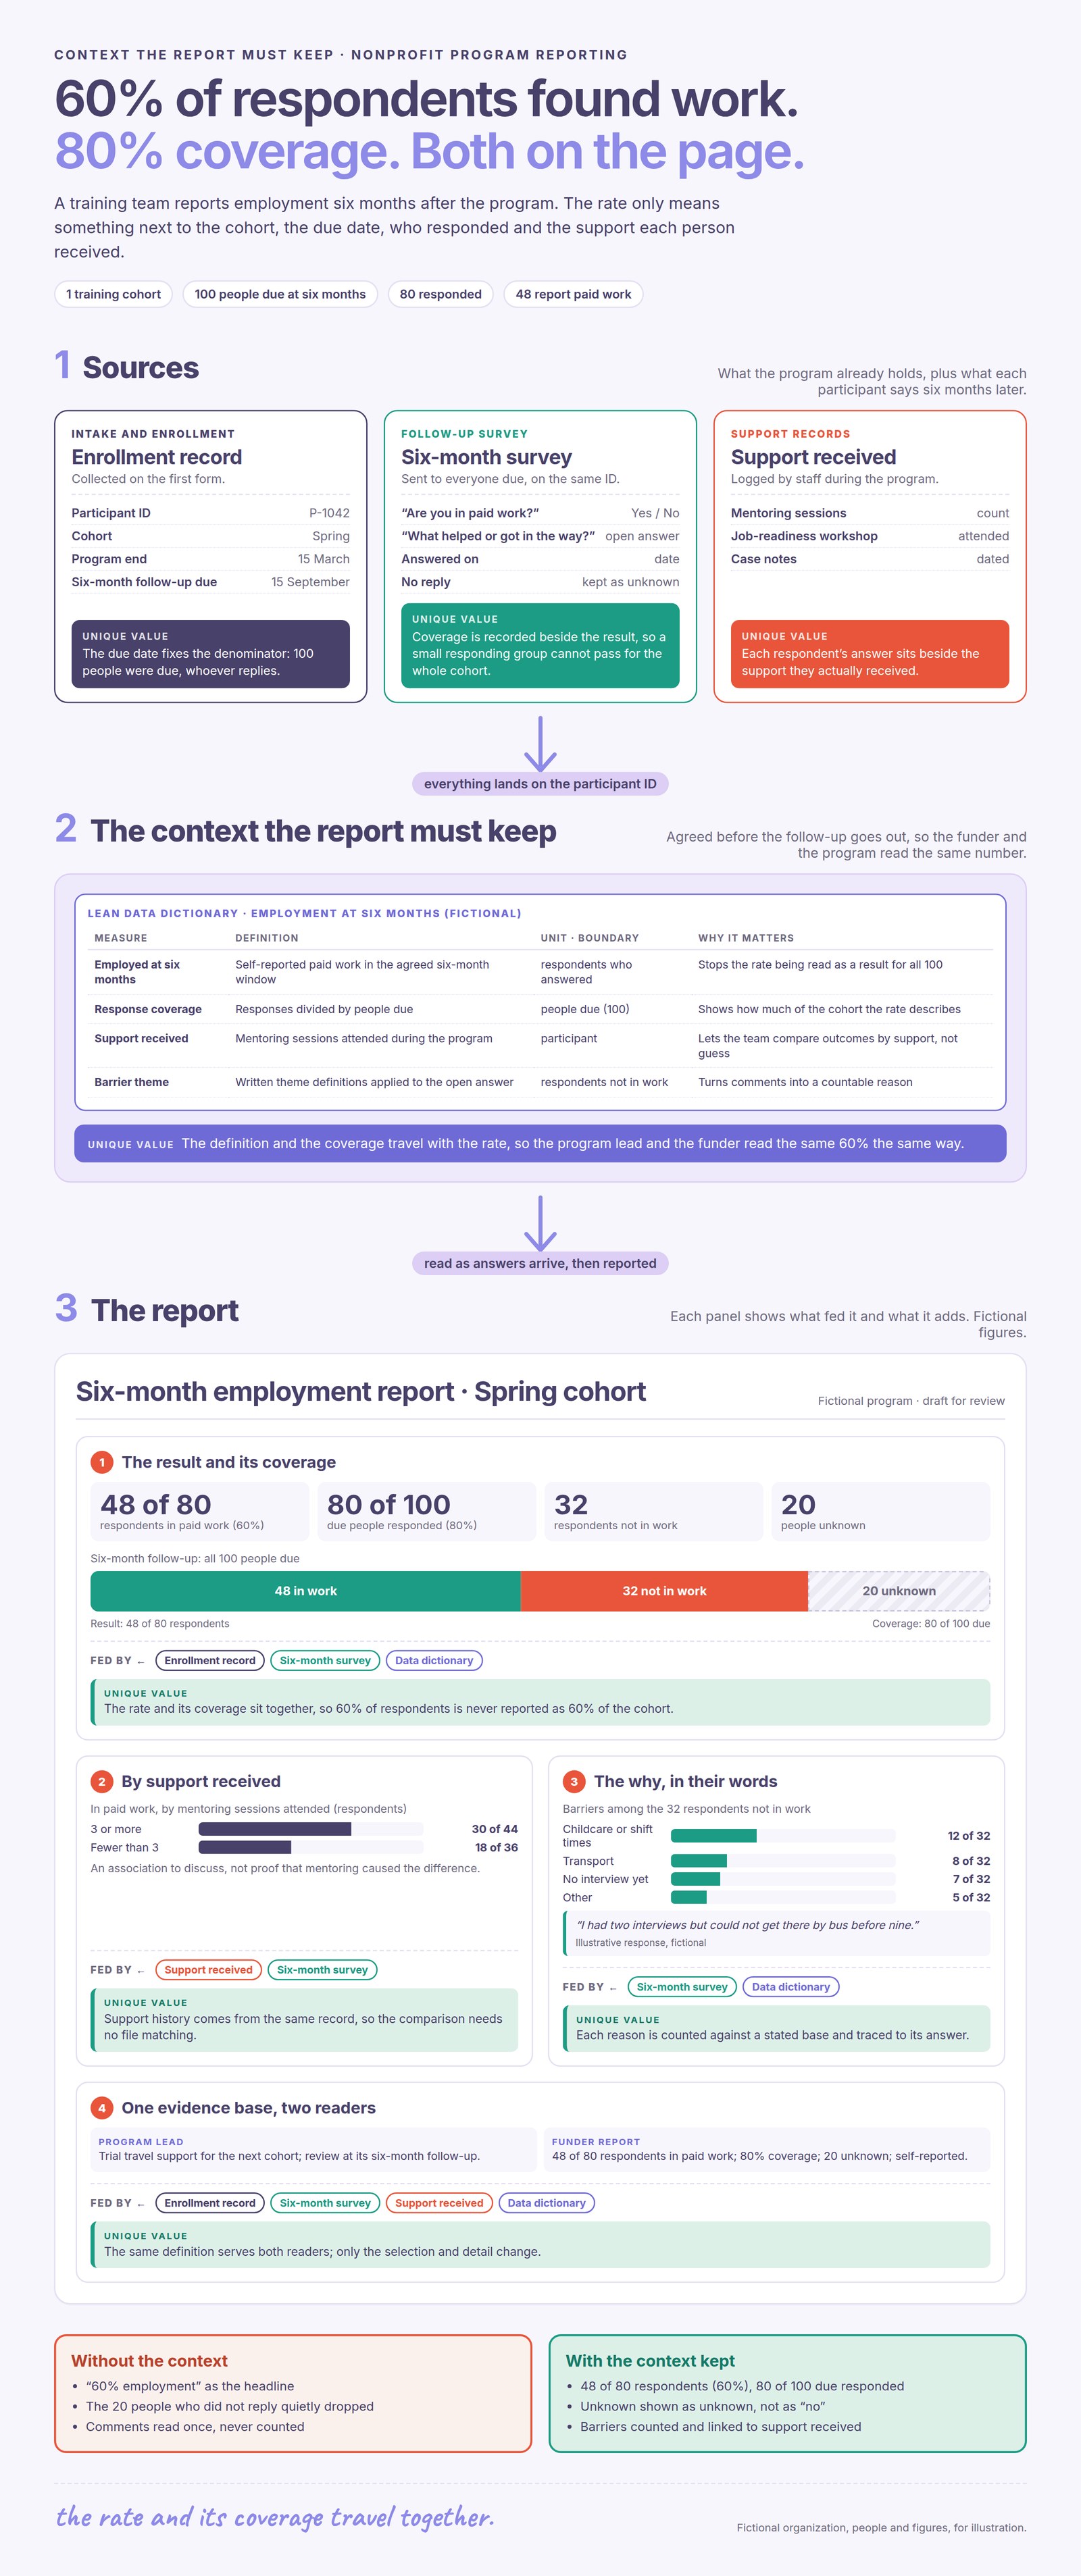
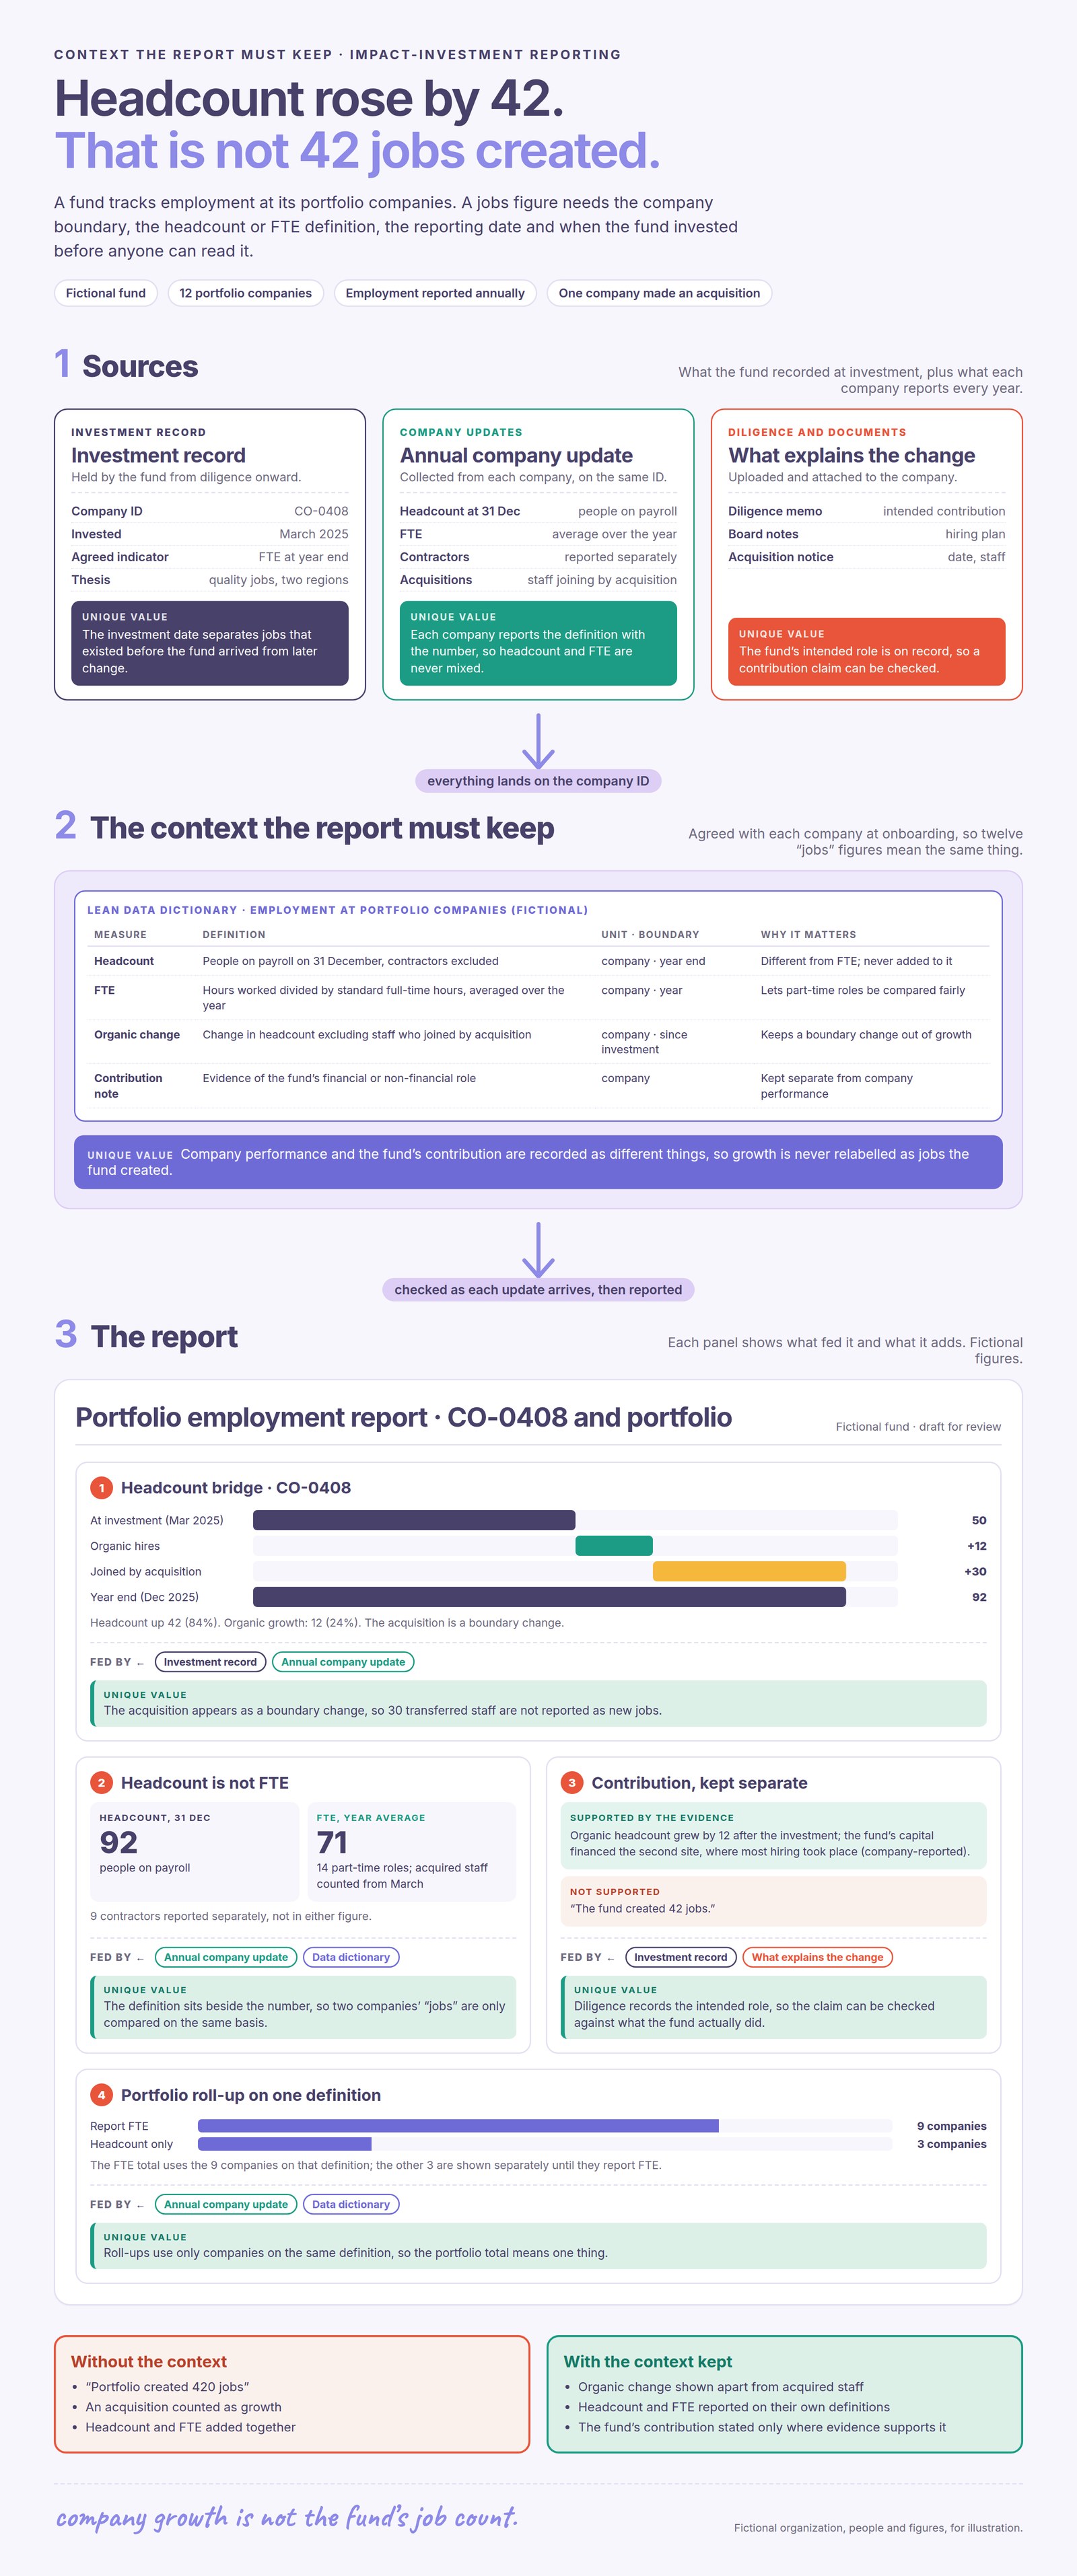
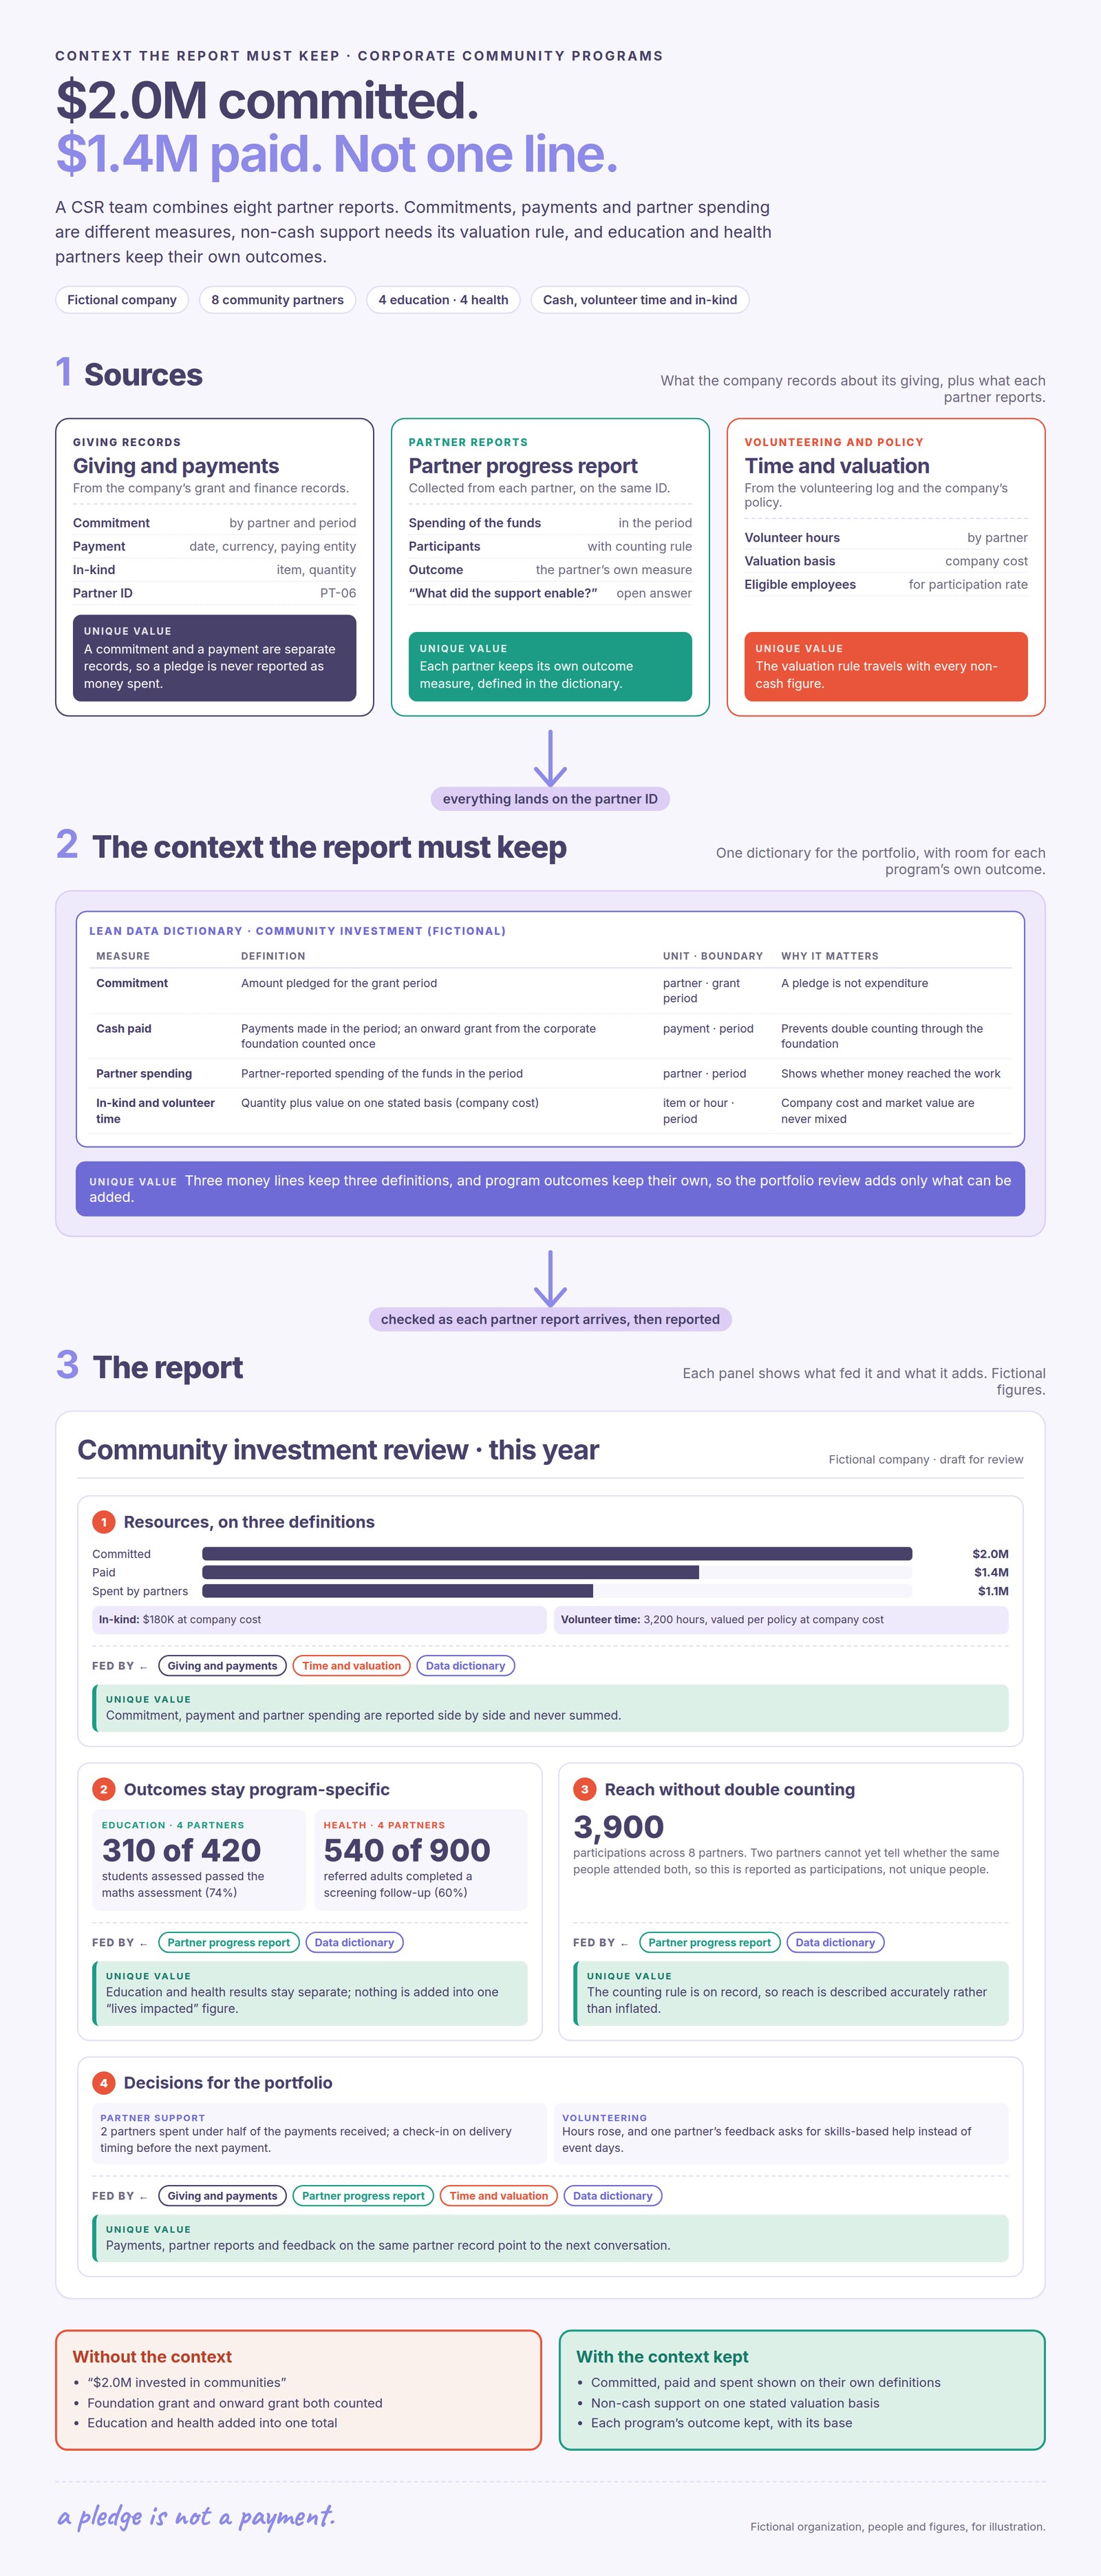
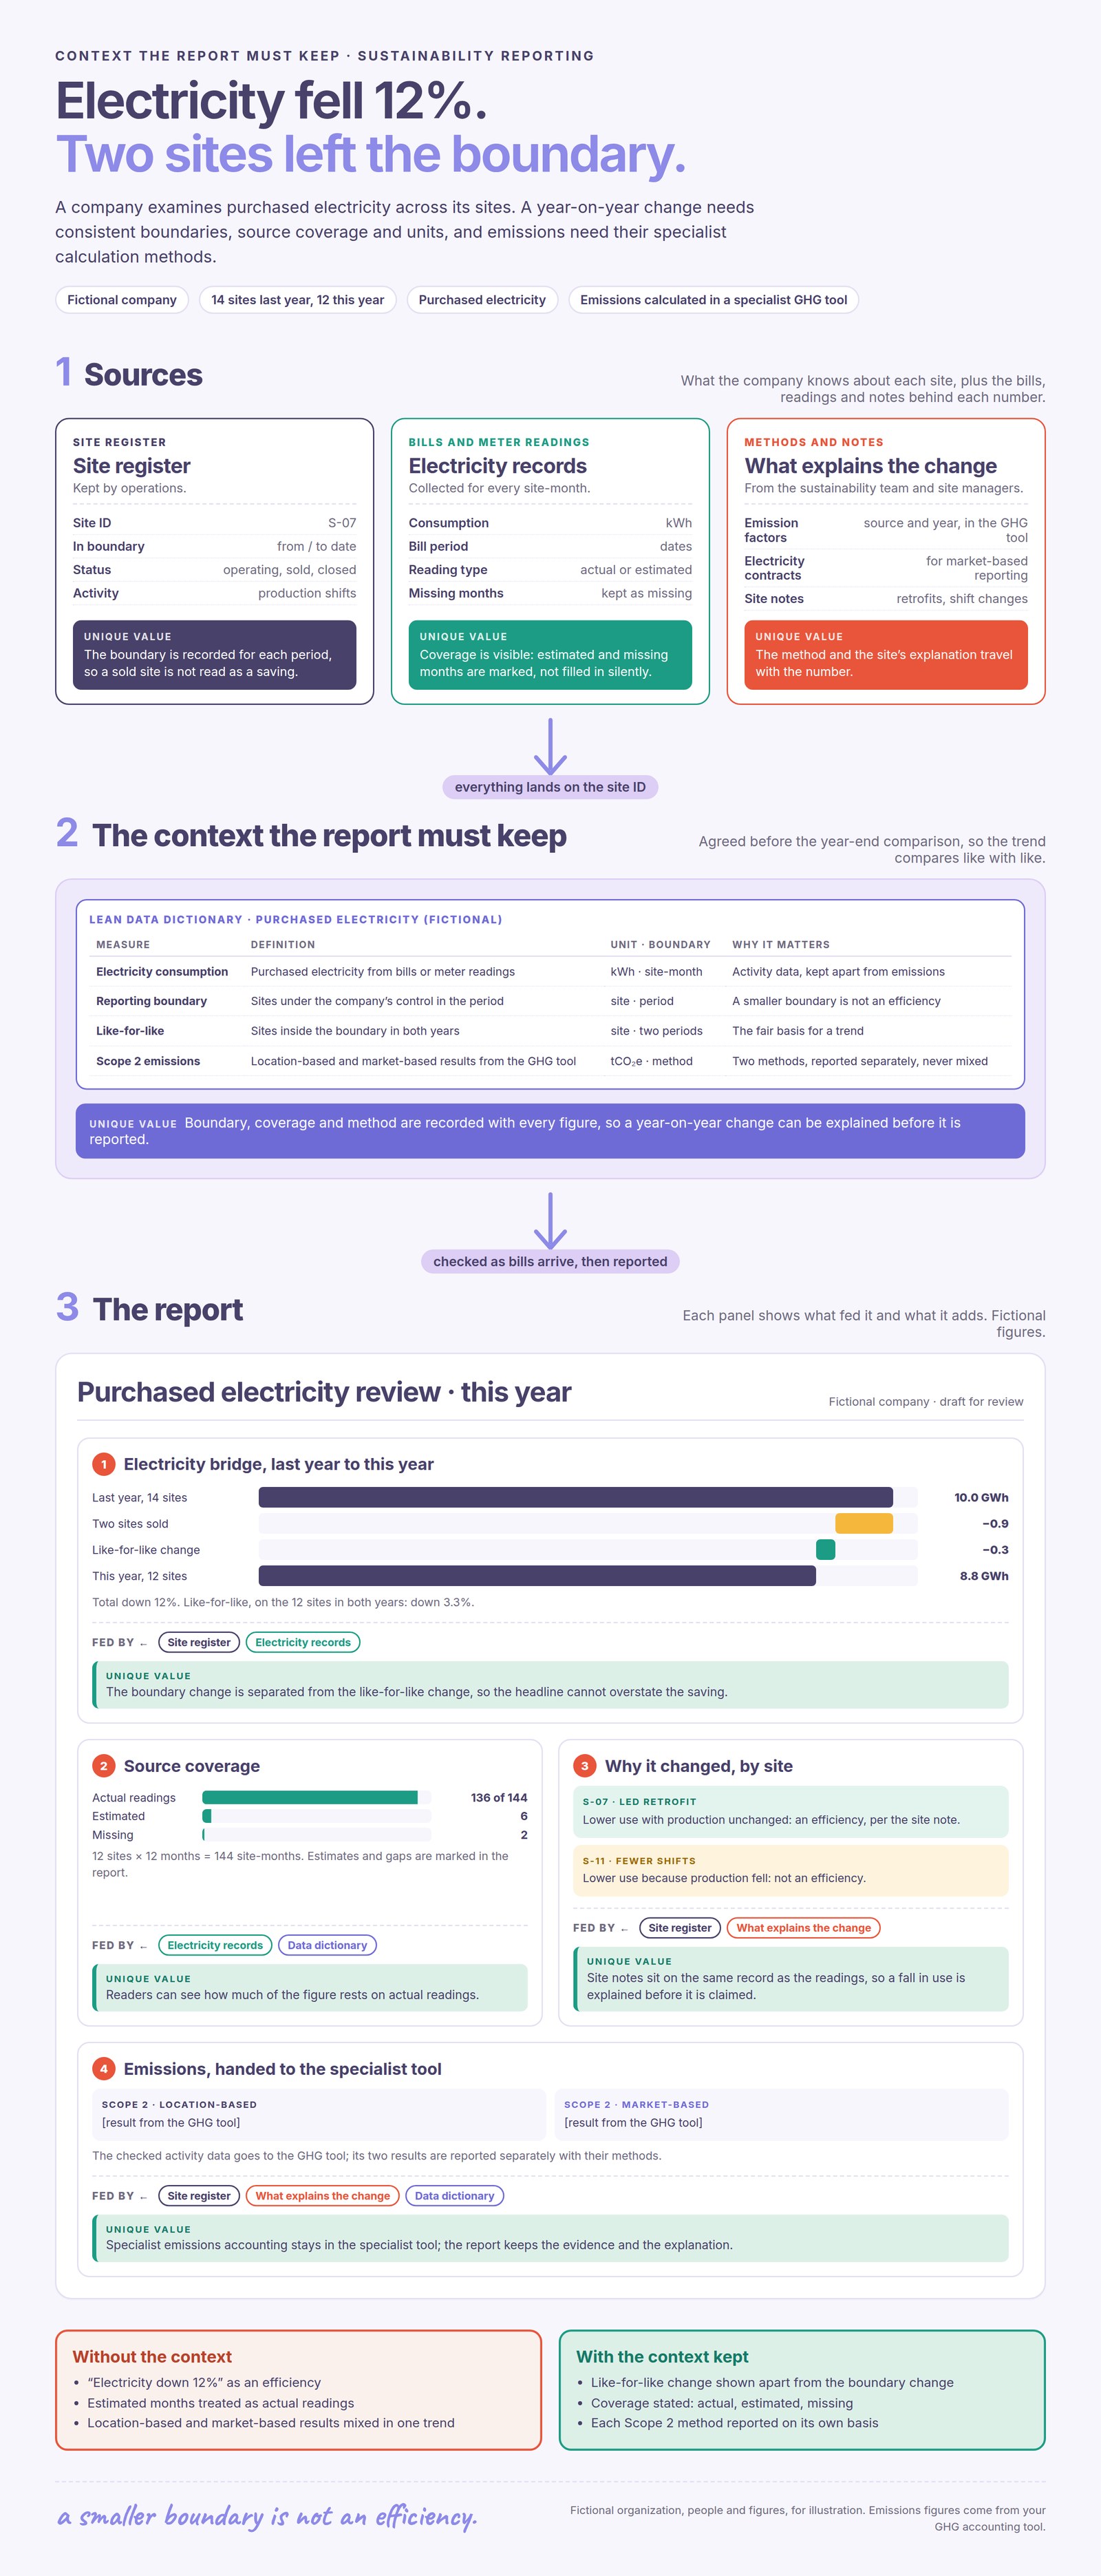
Four fictional report examples, one for each definition above. Select a report to open it at full size; every panel names the sources that fed it.
The dictionary defines the measures. Broader context explains how to interpret them: the program’s purpose, starting conditions, commitments, relevant documents, prior decisions, external conditions and the audience’s question. Both are needed for useful AI analysis.
For a nonprofit, context may connect an application, baseline, case notes, assessments and follow-up. For an investor, it may connect the company’s impact thesis, diligence, investment terms, agreed indicators and later updates. For CSR, it may include the grant agreement, partner report, community feedback and corporate valuation policy. Sustainability reporting adds organizational boundaries, methods, material topics and source records from the relevant operations.
This allows a report to explain a result rather than merely repeat it. A higher completion rate may coincide with narrower eligibility. A reported increase in employment may come from an acquired business. A reduction in emissions may reflect a changed boundary. These are questions context helps the team examine; the presence of more documents does not automatically establish the explanation.
Open with the purpose, boundary and period. Present the results against the relevant objective, with populations and coverage visible. Explain differences using the supporting evidence, including negative findings and missing information. Close with decisions, responsibilities and the next review.
A participant-level service review can include detail that does not belong in a public report. A private investor report may contain company information that needs aggregation or exclusion in a public version. Reuse the evidence while applying the appropriate access and disclosure rules.
AI can help organize and draft this account. Review whether each claim uses the intended definition, is supported by the source and distinguishes observation from explanation. A citation makes review easier; it does not establish causation or turn an estimate into an observed result.
Sopact connects forms, files and feedback across programs and portfolios, including quantitative results, qualitative responses, interviews and reports. Configured analysis becomes available as information arrives and can be explored through AI Assistance alongside the relevant history. Staff can use it for partner conversations and program decisions before the formal report is due.
The benefit is continuity: an application or diligence file informs the agreed reporting plan, updates add evidence, and later questions can draw on what the team already knows. Shared definitions make reporting more consistent while program-specific detail explains differences.
Sopact supports that evidence and analysis workflow. Specialist emissions accounting, regulatory interpretation or independent assurance should be scoped separately where required. For the platform selection question, see impact reporting software. For corporate-specific examples, see CSR reporting.
Impact reporting communicates an organization’s contribution to change, the supporting evidence and what results mean for its audience. Useful reports retain purpose, scope, definitions, context and next decisions.
Nonprofit reporting usually centers on programs, participants and funder commitments. Investment reporting connects company outcomes with an impact thesis, portfolio context and the investor’s contribution. Similar metric names can require different definitions.
Include the measure’s purpose, reporting unit, definition, population, period, calculation, aggregation rules, source, owner and version. For rates, preserve the numerator, denominator and coverage.
Definitions tell AI and reviewers what a measure means. Context supplies objectives, prior commitments, history and relevant circumstances so results can be interpreted rather than simply summarized.
They overlap but serve different purposes. Impact reports commonly explain program or investment outcomes. Sustainability reporting can cover wider organizational impacts and sustainability-related financial risks and opportunities under the selected reporting basis.
Continue with a purpose
Related solution
Connect partner evidence with agreed measures and portfolio decisions.
Explore the solution →Continue learning
Agree what each measure means before comparing or reporting results.
Start learning →
Customer story
How a gender-lens initiative put its own framework into a working evidence base.
Read the story →Explore how Sopact can connect your definitions, source evidence and reporting context.
See it with your workflow →