


Related solution
Grantee & Portfolio Intelligence
Connect partner evidence with agreed measures and portfolio decisions.
Explore the solution →


Live webinar: Wednesday, October 7, 2026 | 9:00 AM PT
Building context across your data. In 30 minutes, see how to connect data and definitions across teams, with the right permissions and governance, so scattered data points become intelligence your teams and AI can actually use.
Save your spot (free)USE CASE / PRACTICAL GUIDE
CSR reporting explains a company’s social responsibility commitments, activities, results and how it responds to the effects of its business. A useful report connects those commitments with evidence that employees, communities, leaders and other stakeholders can understand. For community investment, it should show what was contributed, who was reached, what changed and what the company learned.
Corporate responsibility is broader than charitable giving. Operational impacts on communities, employee volunteering and funded partner programs require different evidence. Even within a community portfolio, a training outcome cannot be added to a health outcome, and a pledged contribution is different from money disbursed. Shared definitions make the report interpretable.
AI can help analyze partner reports, survey responses, interviews and operational records together. To produce useful reporting, it needs the company’s objectives, agreed definitions, reporting boundaries and methods around those sources. Sopact connects program and portfolio evidence with that context so teams can explain results, support partners and prepare traceable reports.
Separate what was promised, paid and delivered.
Connect outcomes with partner and participant feedback.
Use current evidence to support partners and report clearly.
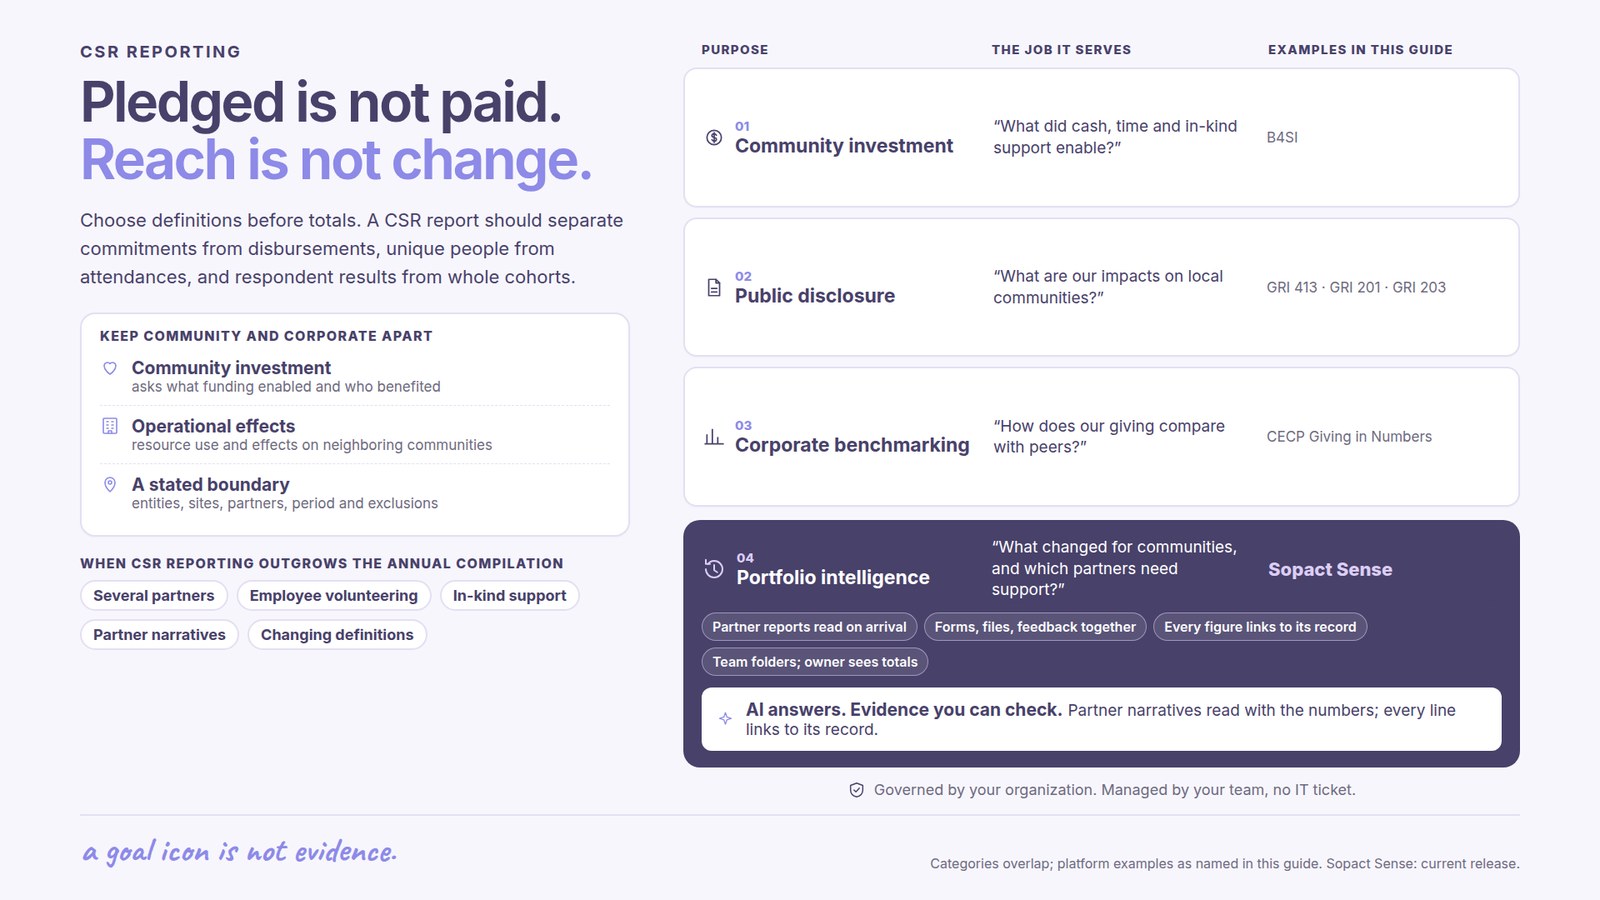
A company may report on both voluntary community investment and the effects of its own operations. A grant to a workforce nonprofit asks what the funding enabled and how participants benefited. A manufacturing-site disclosure may ask about resource use or effects on neighboring communities. Both belong in the responsibility conversation, but they need different evidence and boundaries.
GRI addresses organizational impacts on the economy, environment and people. IFRS S1 focuses on sustainability-related risks and opportunities relevant to capital providers. A report’s audience and selected basis determine which questions it must answer. A community-investment success does not substitute for information about operational impacts.
Define the company entities, sites, programs, partners and period covered. State what is excluded and keep the distinction visible when information is combined in a corporate report. This guide explains the evidence design; jurisdiction-specific disclosure obligations require their own scope assessment.
The B4SI Community Investment Framework connects corporate contributions with activities and changes for communities and the business. It is useful for organizing the measurement of voluntary community investment, including cash, employee time and in-kind resources. Its company-cost basis for in-kind inputs is a reason to preserve the valuation method behind a number.
GRI 413 addresses local-community impacts and their management around an organization’s operations. It should not be reduced to a list of donations. Other relevant disclosures may include community investment within GRI 201 or infrastructure and indirect economic effects under GRI 203. Select disclosures in the context of the organization’s reporting approach and material impacts.
CECP’s Giving in Numbers supports comparison of corporate community investment. Benchmarking requires its definitions and valuation basis, not merely a similar metric name. Keep the underlying quantities and valuation evidence when preparing different reporting views.
The SDG Compass helps businesses connect strategy with the Sustainable Development Goals. Explain the specific target relevant to a program and the evidence of its contribution. A goal icon is not evidence that the program achieved an outcome.
These references serve different purposes. A mapped field or generated report does not establish compliance, certification or independent assurance.
Begin with the reports the team actually needs: a community-investment review, a volunteering account, a partner-outcome review or a broader sustainability disclosure. Work backward from each claim to the data and definitions required to support it.
Identify whether a record represents a payment, volunteer, service visit, participant, partner or site-period. Keep entity, geography and dates with it. A dictionary should say which records are included and when two records refer to the same person or transaction.
Record the unit, numerator and denominator for rates, valuation method for non-cash contributions, and rules for combining results. Preserve program-specific outcomes alongside a common portfolio core. The examples below show the minimum distinctions to agree.
| Measure | Definition to agree | What it prevents |
|---|---|---|
| Cash disbursed | Payments made during the period; currency, funding entity, recipient and transaction source. | Treating a pledge as expenditure or double-counting an internal transfer and onward grant. |
| In-kind support | Quantity, value, valuation basis, date and supporting calculation. | Combining company-cost and fair-market-value estimates without explanation. |
| Unique people supported | Distinct people receiving a specified service, with period and deduplication scope. | Reporting repeated attendance or overlapping partner populations as unique reach. |
| Volunteer participation | Distinct qualifying volunteers divided by the defined eligible employee population. | Changing the denominator between periods or counting repeated volunteers twice. |
| Participant outcome | Outcome definition, eligible cohort, follow-up window, respondents and source. | Presenting a respondent result as a complete cohort outcome. |
| Electricity consumption | kWh by site and period; organizational boundary, source and estimated-data treatment. | Mistaking a boundary change or missing site for improved efficiency. |
Each measure needs a source, responsible owner, review status and definition version. Map it to the chosen reporting reference only after the operational meaning is clear. If the definition changes, explain whether earlier figures are comparable or have been restated.
Show commitments and disbursements by partner, issue and geography, alongside in-kind resources and employee time with their valuation methods. Leadership can see where resources went and where delivery or spending needs clarification.
Present unique volunteers, participation rate, hours and the activities supported. Include partner feedback about whether the contribution met a useful need. Participation is an engagement measure; the community benefit needs its own evidence.
Show results within comparable program groups, with follow-up coverage and the explanations behind differences. For example, an illustrative cohort with 100 people due, 80 respondents and 48 reporting employment has 60% employment among respondents and 80% follow-up coverage. Twenty outcomes remain unknown.
Bring together progress, recurring barriers, partner support needs and agreed follow-up. An illustrative review might show nine partner reports reviewed, two needing clarification and one overdue. Those statuses help allocate attention; they should not be treated as ratings of program impact.
Each report answers a different question using consistent underlying evidence. This is more useful than forcing every initiative into one portfolio score.
Here is a community-investment review built that way, from the giving records, partner reports and volunteering log through to the decisions it supports.
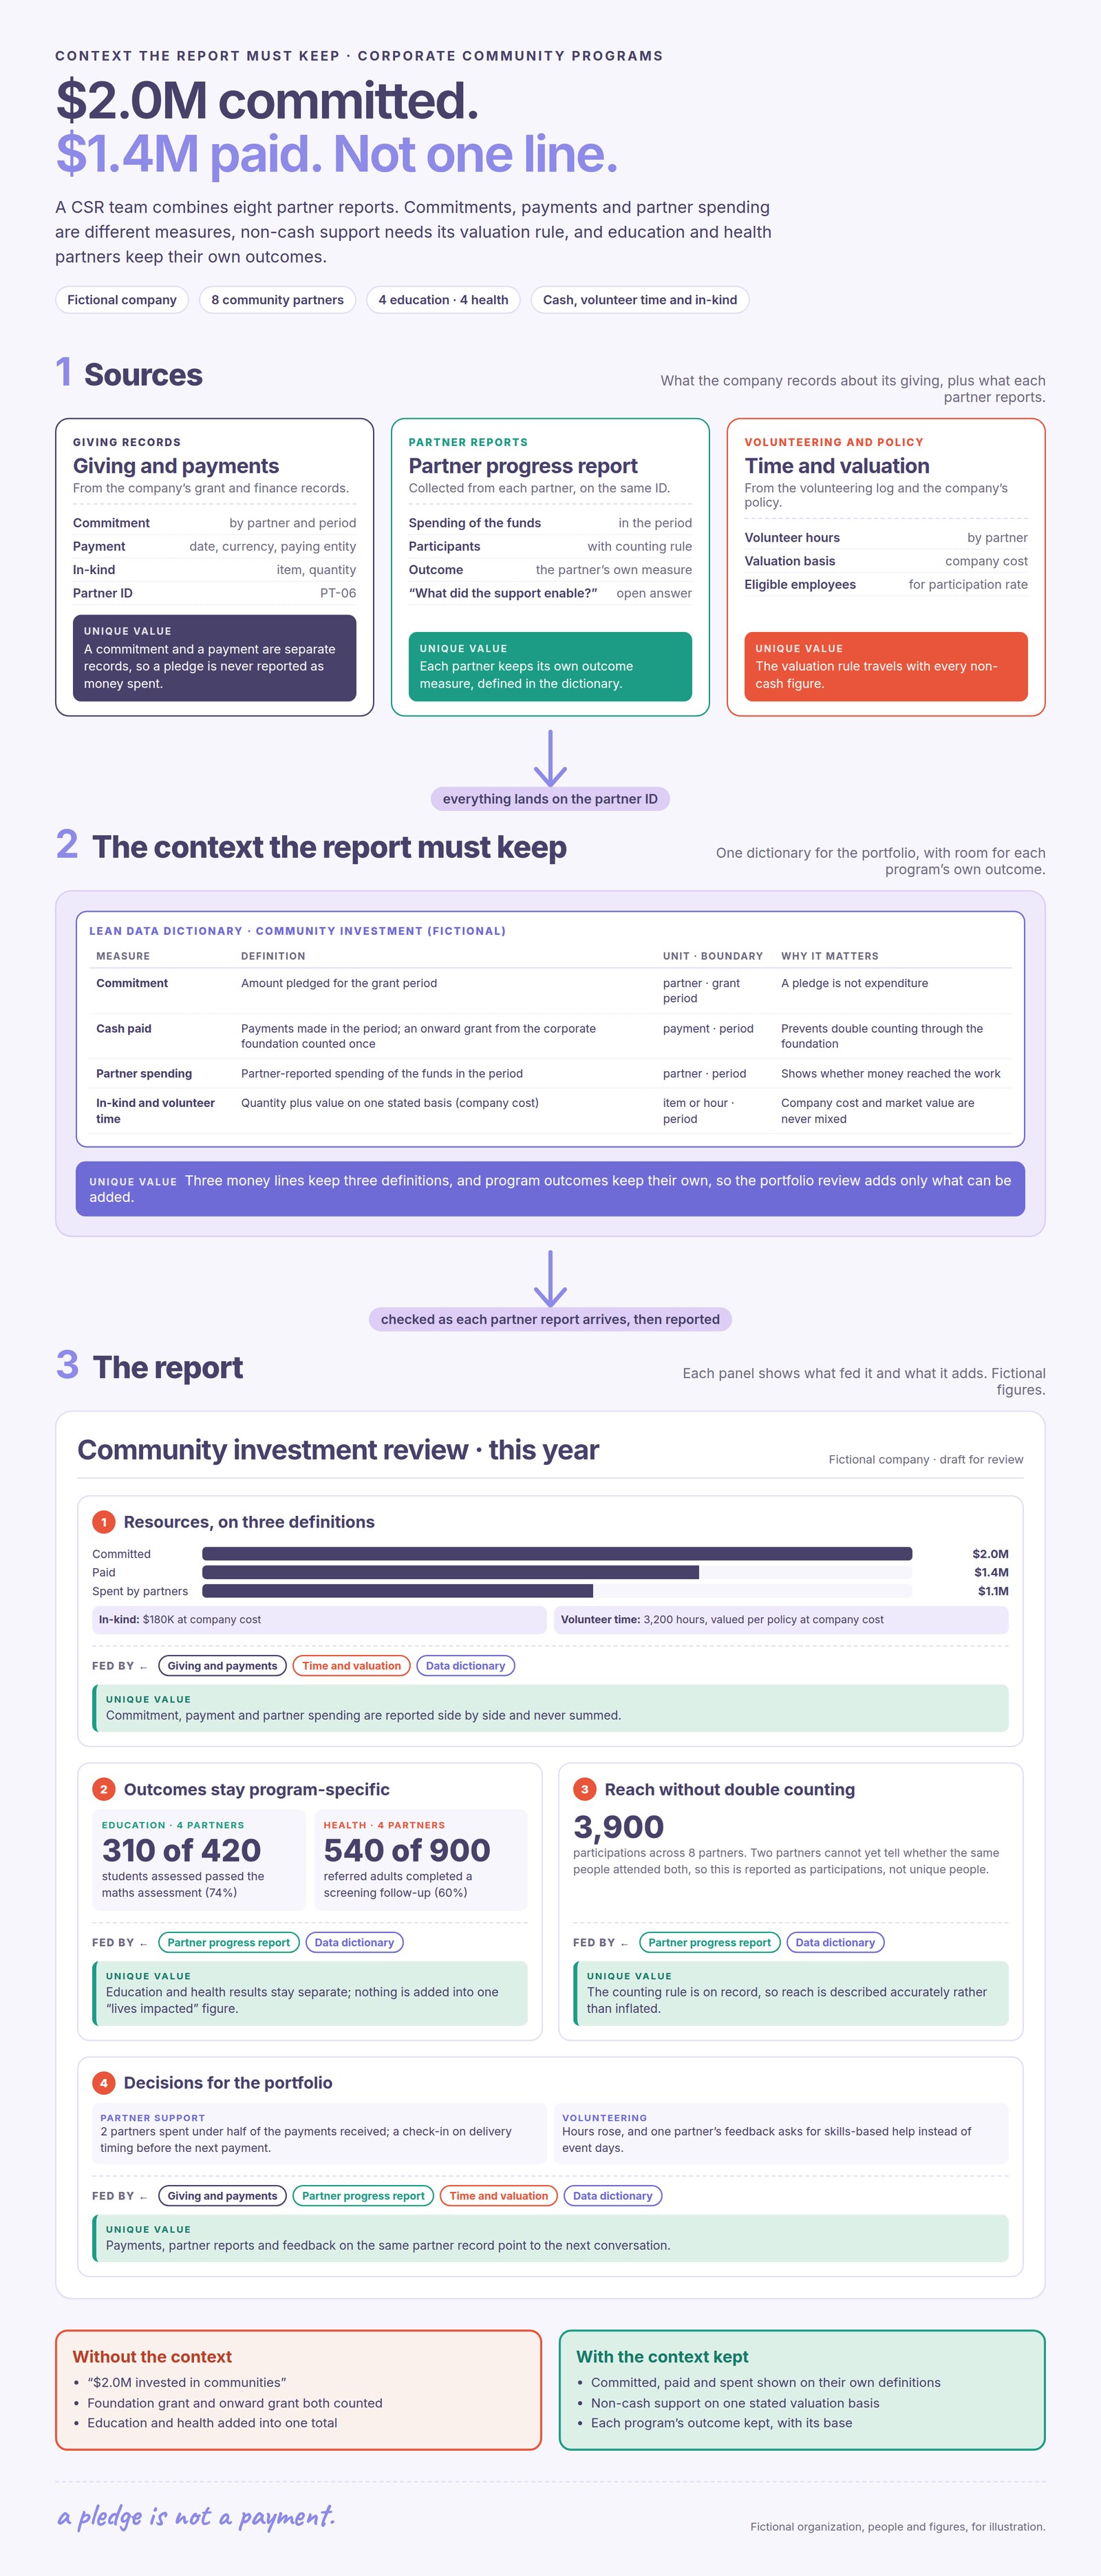
These are illustrative situations, not customer results.
A partner’s total falls because it now reports unique participants instead of attendances. The dictionary change and earlier reporting method explain the apparent decline. Without them, leadership might question a successful program for the wrong reason. With them, the team can establish a comparable baseline and ask about actual outcomes.
The hours show employee contribution, while partner feedback may describe a mismatch between offered skills and the work needed. Reading both alongside the activity brief turns a positive participation headline into a useful planning question: should the next activity change its staffing, preparation or purpose?
The result could reflect efficiency, reduced activity, a divested site or incomplete reporting. Site boundaries, operating context and source coverage help explain which. Keep the activity data and calculation method available so an AI-generated narrative does not automatically describe the fall as an environmental improvement.
Extend the dictionary around the relevant topic rather than putting every sustainability measure into a generic “impact” field. Environmental data may need site, activity, unit, method and estimation details. Labor or community evidence needs the relevant population, organizational relationship, period and source.
For emissions reporting, the GHG Protocol Corporate Standard supports inventory accounting. Preserve the underlying activity data, applicable factors and methods. Scope 2 reporting also needs the basis for the purchased-energy calculation. A narrative summary of utility records is not a completed emissions inventory.
Connect the information to material topics, targets and management actions. Keep corporate inventory figures separate from a funded project’s claimed avoided emissions or offsets; their accounting purposes differ. Sopact can support the collection, context and analysis of evidence, while specialist calculations and formal disclosure requirements remain explicitly scoped.
Sopact connects forms, files and feedback around programs and portfolios. Quantitative results can be examined with partner narratives, interviews and substantial reports, using agreed definitions and program context. Configured analysis is available as evidence arrives, and AI Assistance helps the team explore questions with sources available for review.
This matters when a CSR team needs more than an annual compilation. A partner’s application explains the original commitment; progress updates show what changed; qualitative feedback explains emerging needs. Keeping that evidence connected makes it useful for support, renewal and later reporting.
The team retains local program detail alongside shared measures. It can compare relevant groups without pretending that a health result and an employment result mean the same thing. Knowledge remains available as colleagues and reporting priorities change.
Sopact’s focus here is portfolio intelligence. Existing systems can continue to administer giving, payments or volunteer logistics where they serve those needs well. Data exchange should be scoped around the sources and access actually available.
Choose a report that currently demands substantial consolidation and identify the decisions it should support. Agree the reporting boundary, shared definitions, relevant partner sources and who reviews the claims. This gives the first workflow a useful purpose beyond producing another document.
Sopact’s typical setup estimate is two days to two weeks for an agreed scope. Your team manages routine collection and analysis with personalization and continuing support. The practical benefit to assess is less repeated preparation and clearer, earlier partner decisions.
For the platform’s role, see CSR software for portfolio intelligence. For the structure of a credible account of outcomes, continue to impact reporting.
CSR reporting explains a company’s responsibility commitments, activities, results and response to its effects on stakeholders. Community-investment reporting is one part of that broader account.
B4SI supports community-investment measurement, relevant GRI disclosures support public reporting, CECP supports corporate benchmarking, and SDG targets support strategic alignment. They have different purposes and definitions.
For each measure, record its definition, unit, period, population, source and aggregation rules. Distinguish commitments from disbursements, unique people from attendances, and respondent outcomes from whole-cohort results.
AI can help analyze partner reports and feedback alongside quantitative results, making evidence available for current questions and later reporting. Shared context and source review remain essential to interpreting findings correctly.
A program report explains corporate support and community results. Sustainability reporting can cover the organization’s wider operations and value chain, with specific boundaries and methods. Keep each report’s purpose and evidence basis explicit.
Continue with a purpose
Related solution
Connect partner evidence with agreed measures and portfolio decisions.
Explore the solution →Continue learning
Build shared definitions while preserving each program’s reporting needs.
Start learning →
Customer story
How a gender-lens initiative put its own framework into a working evidence base.
Read the story →See how Sopact connects partner evidence with the decisions and reports your CSR team needs.
See it with your workflow →